
For nearly four decades, the federal government has quietly operated a high-stakes real estate program with a singular, urgent mission: buying out homeowners living in disaster-prone areas to encourage permanent relocation to safer ground. Run by the Federal Emergency Management Agency, this initiative under the Hazard Mitigation Grant Program has poured more than $6 billion into acquiring over 53,000 properties nationwide. Yet, despite its longevity and substantial financial footprint, a persistent question has shadowed the endeavor: To what extent does this ambitious managed retreat approach actually work?
A comprehensive study published in Science Advances offers the latest and most rigorous answer to that question. Authored by Rachel Young, an environmental economist at the University of Minnesota, the research reveals that the federal buyout program has largely succeeded in its primary objective of moving people out of harm’s way. Crucially, the study shows that the program has largely paid for itself by preemptively avoiding future disaster damages, emergency response expenditures, and recurring insurance payouts.
However, the findings also deliver a sharp cautionary note: the program’s successes are not distributed equally across American society.
"The program is extremely effective at helping people not only move, but also move to lower-risk places," said Young, whose paper underscores that the tangible benefits of federal managed retreat are unevenly distributed among participating households and communities.
FEMA’s foray into property buyouts began in 1988, born out of a fiscal and humanitarian necessity to break the cyclical loop of repeatedly paying federal disaster aid or insurance claims at the exact same geographic coordinates. Without intervention, high-risk properties could become endless drains on public resources. Investigative reporting by ProPublica highlighted the extremes of this phenomenon, documenting cases such as a single home in northeast Houston that received 18 separate federal flood insurance payouts totaling $1.8 million—roughly 15 times the actual market value of the property. Buyouts were designed to permanently eliminate these recurring liabilities by removing the structures entirely and converting the land into permanent open space.
The mechanics of the program rely on local administration. Residents apply through their local or state governments, which in turn request federal funding that typically covers 75 percent of the property’s appraised pre-disaster market value. If the application is approved, the government extends a buyout offer to the homeowner, who retains the ultimate autonomy to decide whether to accept and walk away.
Using a sophisticated blend of public and private data to track the long-term trajectories of participants, Young’s paper discovered that program participants were roughly 20 percentage points more likely to successfully relocate within the first five years following an event compared to control groups of similarly impacted homeowners who did not receive buyouts. Although that statistical difference diminished slightly over time, the elevated likelihood of relocation persisted for at least 15 years. Furthermore, the research tracked positive socioeconomic shifts among participants, who tended to relocate to census tracts characterized by higher average incomes, better educational attainment, and higher employment rates. Additionally, data indicated that participants’ debt levels fell, at least in the short term, providing a financial cushion after a crisis.
From the perspective of the federal government and taxpayers, the program has proven to be a fiscal success story. Young noted that as long as administrators effectively target vulnerable populations and ensure they transition to properties with significantly lower risk profiles, the initial federal investment tends to pay for itself through averted disaster claims and reduced long-term emergency response costs.
Despite these macroeconomic wins, the study uncovered stark demographic disparities that threaten the equity of the federal adaptation framework. Participants hailing from higher-income neighborhoods were significantly more likely to successfully relocate and land in areas offering greater economic opportunity. Conversely, households originating from majority-Black or low-income neighborhoods moved far less frequently and experienced markedly smaller socioeconomic improvements when they did relocate.
External experts praised the study for scaling up what had previously been observed only in localized contexts.
"This work is super important," said Jim Elliott, a sociologist at Rice University whose academic focus centers on structural inequities in disasters and recovery. His assessment was echoed by A.R. Siders, director of the University of Delaware’s Climate Change Science and Policy Hub. "This is something people have shown at smaller scales," Siders said. "It’s good to see it on the national level."
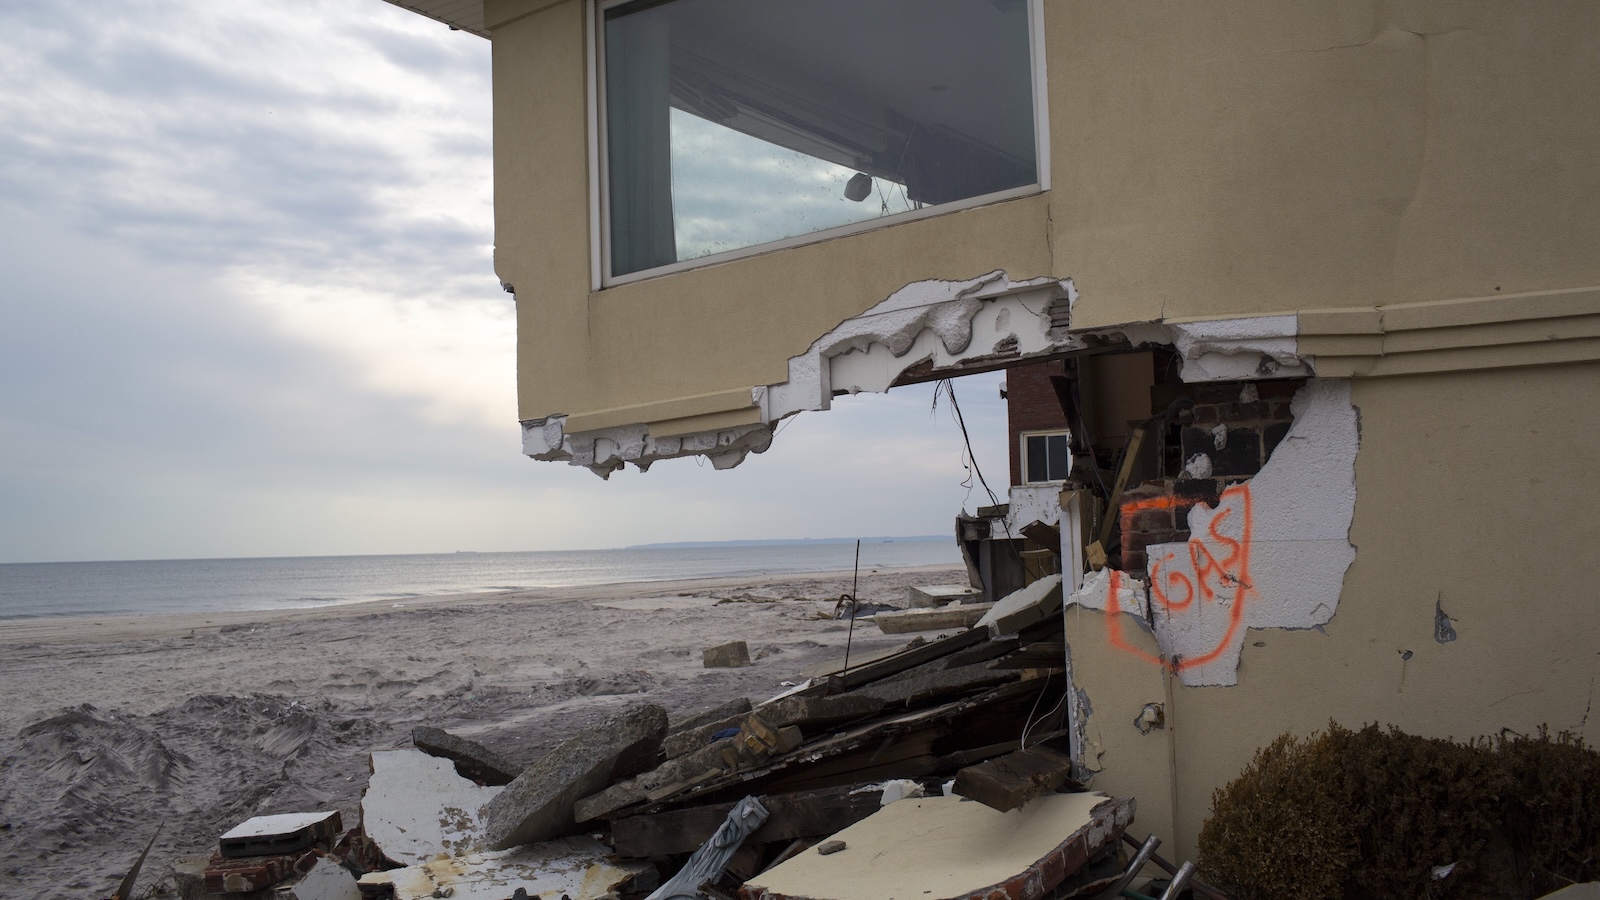
Neither Elliott nor Siders was involved in the drafting of the new study, but both agreed that its findings validate and expand upon a growing body of academic literature indicating that while the buyout framework functions reasonably well, it is in desperate need of structural modernization.
Reducing administrative wait times and baking equity directly into the program design are paramount, Elliott said. He pointed out a fundamental disconnect in how the government and affected homeowners perceive the core purpose of a buyout.
"The government looks at it as a property acquisition program" and "a way to look out for other taxpayers," Elliott explained. "But if you’re from a damaged home, you’re looking at this as disaster recovery."
The bureaucratic machinery of a government buyout can drag on for years, leaving vulnerable disaster victims trapped in a state of precarious limbo while they await bureaucratic decisions and funding approvals. Even when a buyout is ultimately approved, Elliott warned that relying exclusively on pre-disaster market values can exacerbate pre-existing societal inequalities. Homes located in historically marginalized or economically depressed communities naturally command lower market values from the outset. Consequently, when the government offers to buy these properties based on those depressed values, owners receive far less capital to fund their relocation. In many cases, the government’s check falls drastically short of the cost of purchasing a new home elsewhere, effectively pricing families out of safer geographic areas.
These systemic disparities are vividly illustrated in Young’s empirical data. The average buyout payment amounted to just $40,583 in areas with majority-Black populations, compared to a starkly higher $93,977 in census tracts with high proportions of white residents. Similarly, the estimated increase in the likelihood of relocation was approximately 18 percentage points in tracts with smaller Black populations, compared to a meager 6 percentage points in majority-Black tracts.
The buyout program "should do better and be more equitable," Elliott asserted. However, he cautioned that equity reforms, while necessary, address only a fraction of the challenge. The broader, more systemic crisis is that the federal program simply is not reaching the millions of Americans currently living in precarious, disaster-prone housing.
"This is important, but it’s not sufficient," Elliott said of the potential fixes. "It’s buying us some time."
Young expressed hope that empirical research of this caliber will empower policymakers to refine, strengthen, and potentially scale up property buyouts as a primary tool for national climate adaptation, even as political headwinds—such as the spending restrictions championed by figures like former President Donald Trump—frequently constrain FEMA’s financial bandwidth. Looking internationally, Elliott pointed to structured managed retreat programs in countries like New Zealand and various European nations that could serve as policy blueprints for the United States. Siders emphasized that the study reinforces the urgency of implementing long-debated reforms to FEMA’s guidelines, such as transitioning from pre-disaster market valuations to replacement cost models to ensure marginalized groups have the financial means to relocate safely.
Ultimately, all three researchers concurred that a tremendous amount of work remains to be done to diagnose the root causes of these persistent inequities and to formulate effective remedies—responsibilities they argue should be spearheaded by the federal government itself rather than external researchers.
"The federal government doesn’t do anything to assess where people go after the program," Young observed. Elliott noted that tracking the long-term human outcomes of government policies routinely falls to academic researchers who must navigate restricted access to sensitive administrative data.
"It was sort of left to us to figure out what the implication of the policy is," Elliott said. "That’s backwards."