
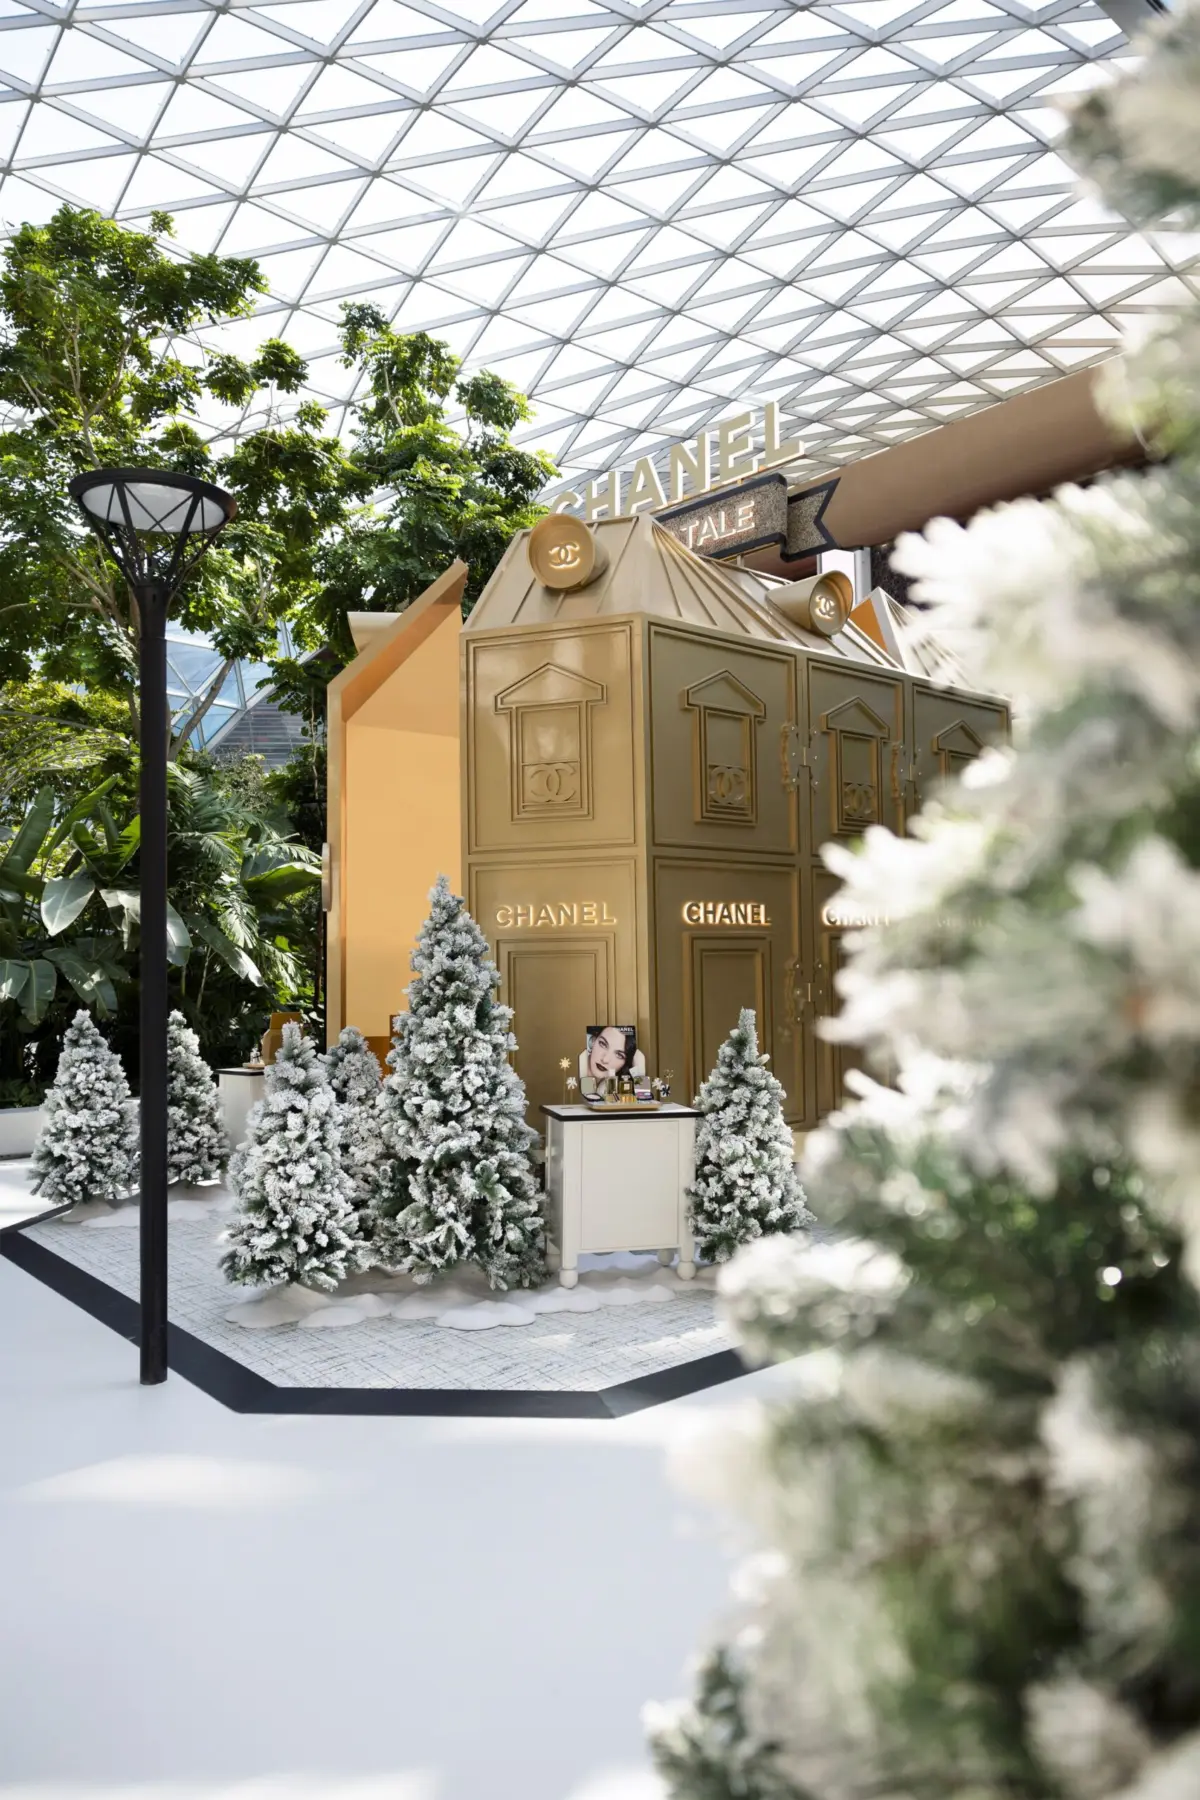
More people than ever are taking to the skies, with global airport passenger traffic reaching a staggering record of 9.8 billion in 2025. Yet, for the beauty industry—one of the most lucrative and vital pillars of travel retail—this surge in foot traffic has not translated into a corresponding boom in sales. In fact, for many, the recovery that followed the pandemic years remains frustratingly elusive, revealing a widening chasm between the volume of travelers and their willingness to engage with airport retail.
Global travel retail serves as a critical ecosystem for the beauty sector, spanning duty-free stores, downtown shopping hubs, airlines, and cruise ships. It has long been the premier platform for brand building and global distribution, providing brands with captive access to millions of international travelers. Historically, the model was straightforward: skincare reigned supreme in North Asia, driven by Chinese consumer demand; Western markets relied on the reliable draw of fragrances; and the Middle East thrived on luxury gifting. According to Generation Research, beauty remained the undisputed leader of the $76 billion global duty-free and travel retail market in 2025, accounting for 32.2% of total sales.

However, the foundational logic of this model—built on the promise of duty-free savings and the convenience of a captive audience—is under intense pressure. While passenger numbers have rebounded in record-breaking fashion, spending growth has stalled. Consulting firm Oliver Wyman suggests that the industry’s failure to keep pace with the influx of travelers has cost it approximately $5 billion since 2023. Today’s travelers are increasingly sophisticated and well-informed; they arrive at terminals with a clearer understanding of market value and far more options, making the traditional "duty-free" pitch less persuasive than it was a decade ago.
The numbers reflect this systemic shift. In the first half of 2026, global travel retail sales across fragrance, skincare, and makeup fell by 5.6% to $13.8 billion. The downturn is not uniform, however, with the Asia-Pacific region serving as the most significant drag on growth. Sales in the region plummeted by 12.1% during the same period, primarily due to structural changes in Mainland China. The crackdown on "daigou" gray-market resellers, the rise of powerful domestic retail competitors, and the repatriation of beauty spending within China have effectively dismantled the traditional duty-free arbitrage model. Given that Asia-Pacific has historically accounted for more than 60% of global beauty travel retail sales, the tremors in China are being felt across the entire global industry.

Geographically, the map of growth is being redrawn. While Europe and the Americas posted sales increases of 8.9% and 9.8% respectively in early 2026, the Middle East and Africa—previously a reliable engine of growth—saw a 3.9% decline. This contraction is largely attributed to regional travel disruptions in the Gulf linked to the ongoing US-Iran conflict.
Beyond the Chinese Traveler: Understanding New Consumer Missions
As the industry grapples with these shifts, retailers are realizing that the old reliance on a singular, dominant traveler profile is no longer sustainable. Britta Hoffmann, director of commercial global beauty at the major retailer Gebr. Heinemann, notes that the industry is being forced to pivot. "What is changing most is not only where travelers come from, but how they shop," Hoffmann explains. "Today’s beauty consumer is more informed, more digital, and more selective. Rather than focusing on nationality, we need to focus on understanding different traveler missions, preferences, and spending occasions."

The demographic shift is also significant. Millennial and Gen Z shoppers, who now account for 61% of global airline travel spending, are expected to represent nearly 80% of that segment by 2035, according to the Oliver Wyman Global Travel Retail Pulse report. Crucially, these younger travelers behave differently: 49% of Gen Z travelers are likely to make an impulse purchase after discovering a new product in an airport setting, compared to just 35% of baby boomers.
Yet, technology has created a double-edged sword. With AI, social media, and real-time price comparison tools at their fingertips, travelers are researching products long before they step foot in a terminal. According to research released in October by the consultancy Kearney for the Tax Free World Association (TFWA), 64% of travelers who used digital tools to research products ultimately walked past airport stores without making a purchase. Nearly half of the respondents expressed skepticism regarding whether duty-free prices actually offered a genuine advantage over domestic retail.

Felipe Grant, global travel retail president at the fragrance giant Puig, sums up the industry’s primary challenge: "Passengers are not shoppers. They have to be converted into shoppers."
Fragrance as the New Anchor for Beauty
If the traditional transactional model is failing, how can retailers reclaim the traveler’s attention? The answer, increasingly, lies in experience-led retail. Gebr. Heinemann is shifting its strategy to combine personalized services with curated, exclusive assortments. At the same time, retailers like Qatar Duty Free (QDF) are proving that success is possible when the retail environment is treated as an extension of the hospitality experience. Thabet Musleh, chief retail and hospitality officer at Qatar Airways, emphasizes that simply placing prestige brands on shelves is no longer enough. "The more thought, care, and creativity we put into curating that experience, the greater customer satisfaction and sales we inevitably get back," Musleh says.

Fragrance has emerged as the most resilient category in this new environment. It was the only major beauty subcategory to see growth in the first half of 2026, with sales rising 5.9%. Fragrance’s share of the global beauty travel retail market jumped from 35.7% to 40.1%. At QDF, niche fragrance sales surged 35% year-on-year, signaling a clear appetite among travelers for more experimental, complex, and individualistic scents.
Brands like Sol de Janeiro have successfully leveraged this trend, evolving from bodycare specialists into scent-led powerhouses. "Fragrance has taken such a big place in our customers’ hearts," says CEO Jordan Saxemard. Meanwhile, luxury houses are using travel retail for "scarcity marketing," such as Puig’s airport-exclusive pre-launch of Carolina Herrera’s La Bomba. By launching in the travel channel ahead of the domestic market and without mainstream media support, the company successfully generated hype and a sense of exclusivity that traditional retail might struggle to replicate.

Reimagining the Airport Retail Experience
The question of whether to buy at an airport is becoming a test of value and differentiation. If a consumer can easily purchase a product on TikTok Shop or at a local Sephora, why bother with the airport?
The Australian beauty retailer Mecca is attempting to solve this by bringing its high-touch, specialist model to Sydney International Airport. In partnership with Gebr. Heinemann, the new space includes a "Beauty Lounge" and a "Mini Mart," designed to cater specifically to the pre-flight mindset. It is a departure from the generic duty-free store, focusing instead on discovery and service.

This trend toward "experiential" retail is echoed by Pierre-Alexandre Koch of Oliver Wyman, who notes that travelers now expect novelty, locally relevant products, and continuously refreshed collections. While the expectation for an 18% price discount relative to domestic markets persists, the future of the channel relies on delivering an experience that cannot be found elsewhere.
For major players like The Estée Lauder Companies, the path forward involves a complete strategic overhaul. Matthew Growdon, president of Asia-Pacific and Travel Retail Worldwide, describes a "Beauty Reimagined" strategy that favors agility and regional customization over a "cookie-cutter" approach. "We’re moving away from the cookie-cutter approach of leading with the same brand in every location," Growdon explains. "If Tom Ford is the dominant brand in a particular market, then that’s the brand we lead with."

This strategy includes prioritizing artisanal fragrance brands like Le Labo and Kilian Paris, which have seen massive success as travelers seek premium, niche offerings. Furthermore, the company is diversifying its portfolio to include more accessible brands like The Ordinary, which has resonated deeply with younger, digital-native consumers.
Ultimately, the travel retail industry is undergoing a painful but necessary maturation. The days of relying on passive, high-volume foot traffic are coming to an end. As brands and retailers move toward more collaborative, data-driven, and experience-focused models, the airport is being redefined from a mere transit point into a powerful platform for customer acquisition. For those willing to innovate and provide genuine, exclusive value, the airport remains one of the most potent stages in the world—provided they can convince the passenger to stop walking and start shopping.