
Insurance is, at its core, a social contract. When a homeowner signs up with a major carrier like State Farm or Allstate, they are confirming their membership in a collective community. Their premiums go toward fixing a neighbor’s burned or flooded home, and in return, that shared pool of capital stands ready to support them in a crisis. Society permits insurance companies to operate within a private market, while electing and appointing public officials to oversee that system and safeguard the interests of policyholders.
That is how the framework is designed to function, but it was far from the reality encountered by Lynn McIntyre.
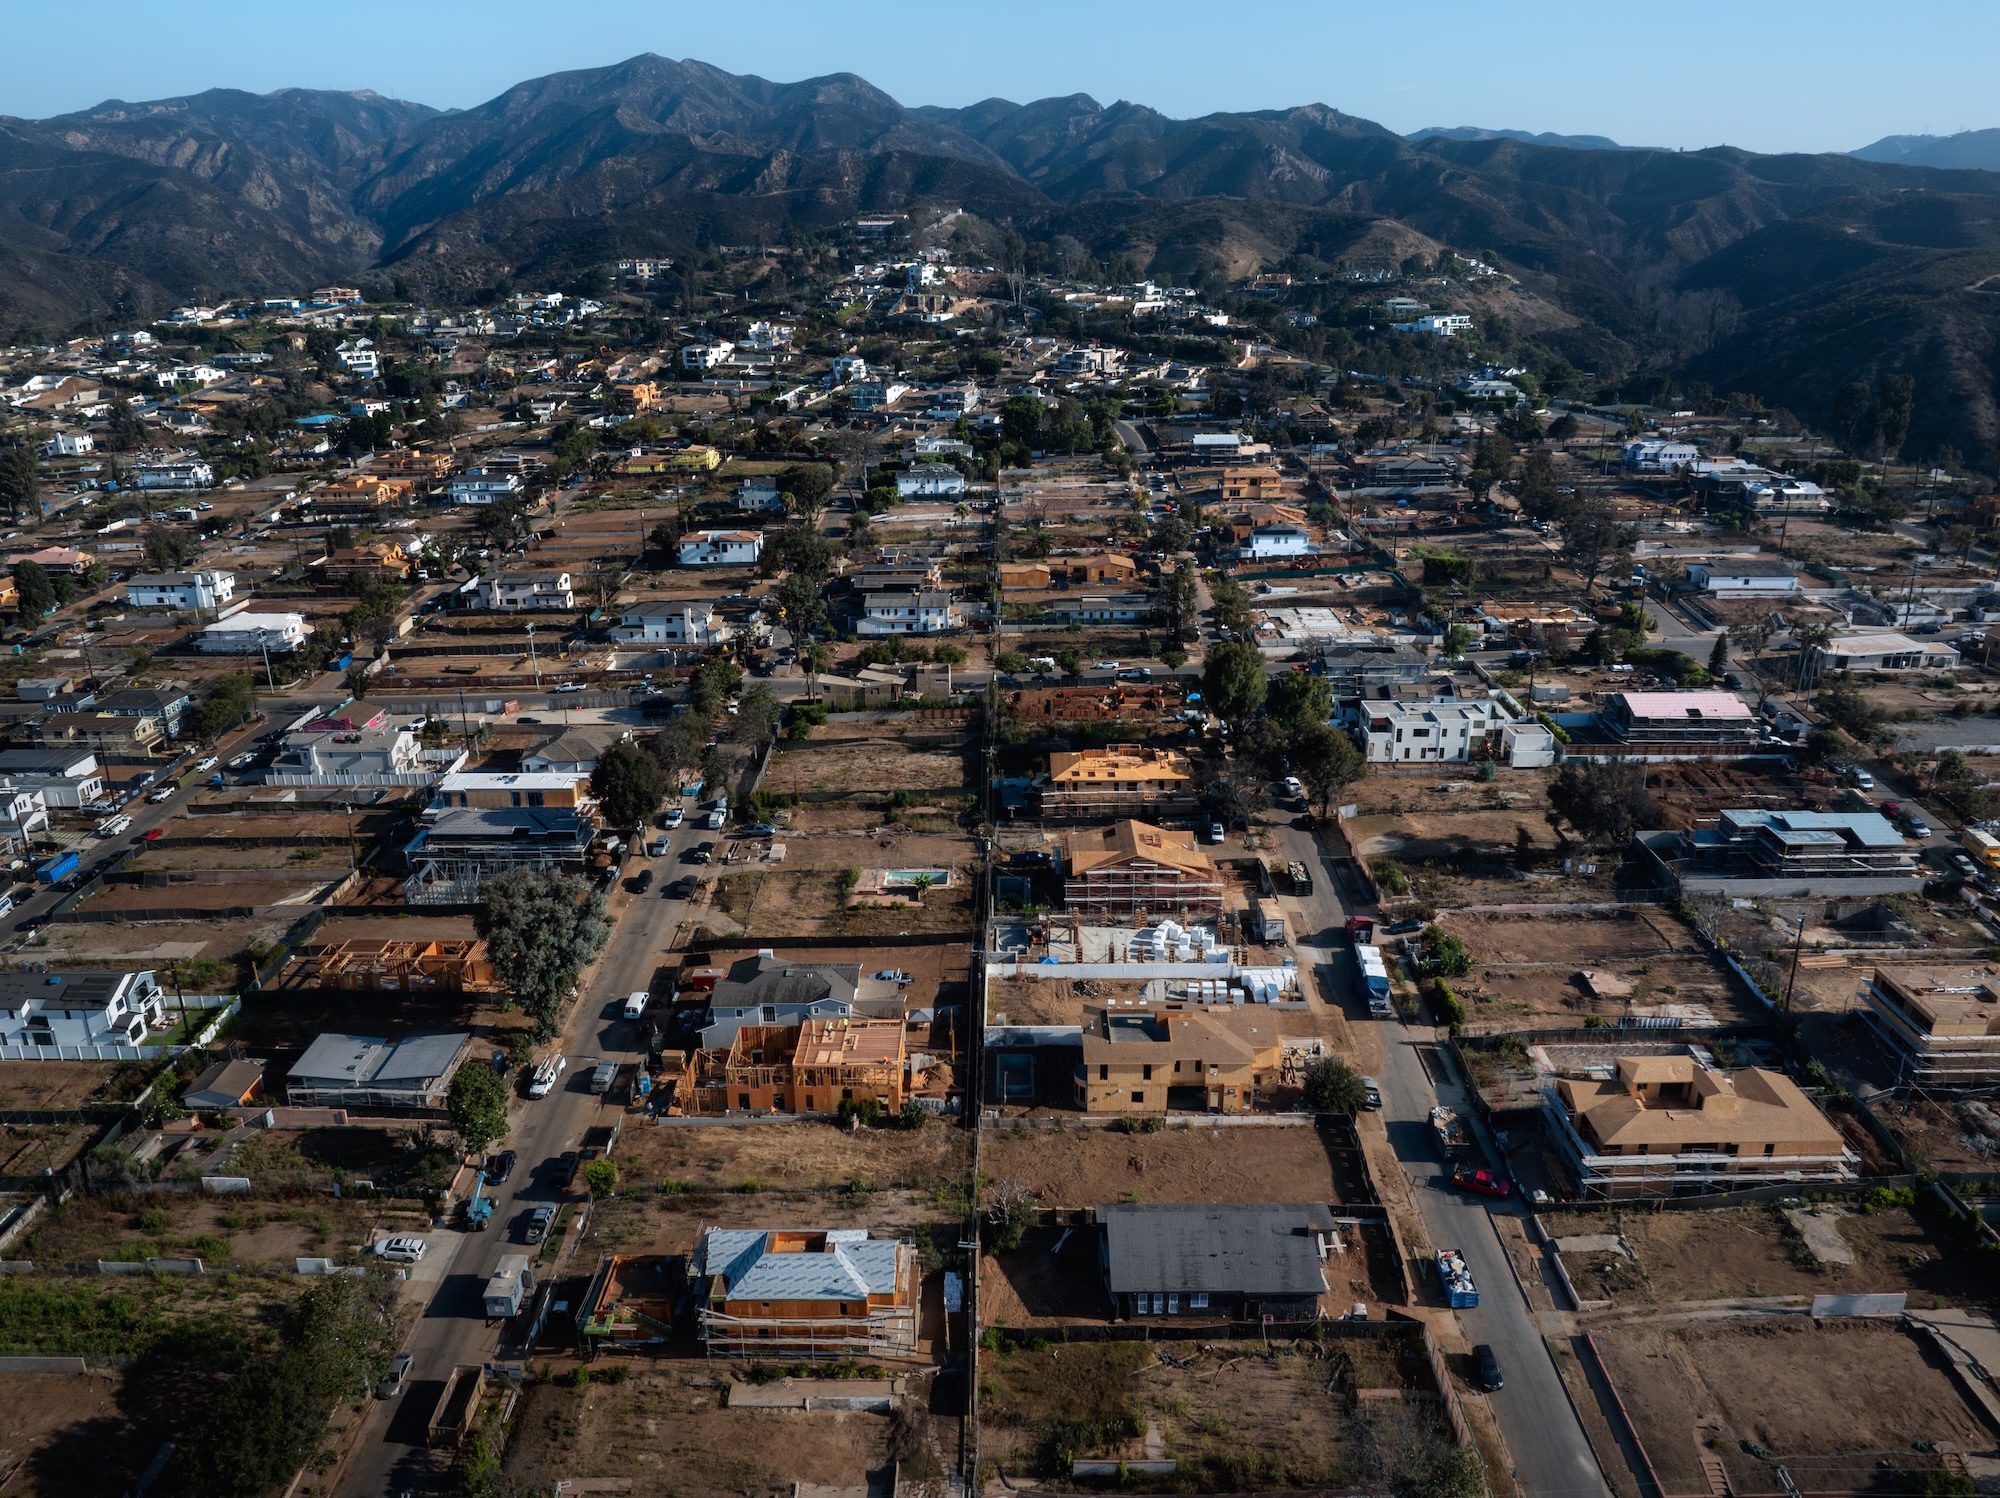
When McIntyre’s mother passed away in 2022, she inherited her longtime home in the "Alphabets," a charming and desirable neighborhood situated not far from the coast in western Los Angeles. McIntyre and her daughter had lived in the residence for just a single year when her insurance provider, Liberty Mutual, abruptly canceled her fire coverage. Finding herself unable to secure another private policy to absorb the property’s wildfire risk, she was forced to enroll in the California FAIR Plan. Functioning as a state-backed "insurer of last resort," the FAIR Plan required her to fork over an additional $5,000 annually, layered on top of her regular homeowners insurance premiums with Liberty.
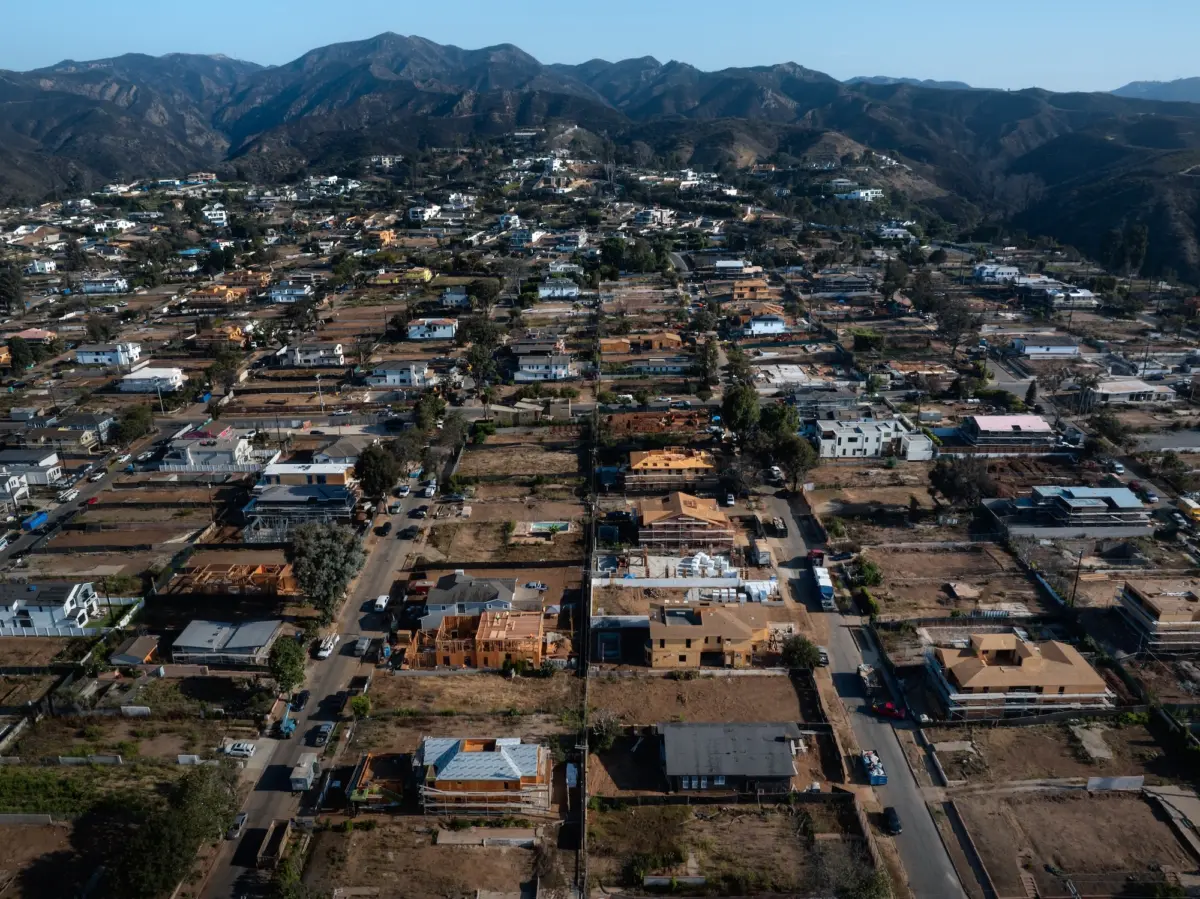
When the Palisades Fire tore through the Alphabet Streets in early 2025, McIntyre’s small bungalow miraculously remained standing. Yet, the interior was saturated with thick smoke and fine ash that had seeped inward through the windows and ventilation systems, leaving her personal belongings stained and ruined beyond recognition. When she filed a formal claim with the FAIR Plan, company adjusters informed her that she was essentially out of luck. They agreed to cover the costs of a temporary apartment, but offered virtually nothing else toward the remediation of her home.
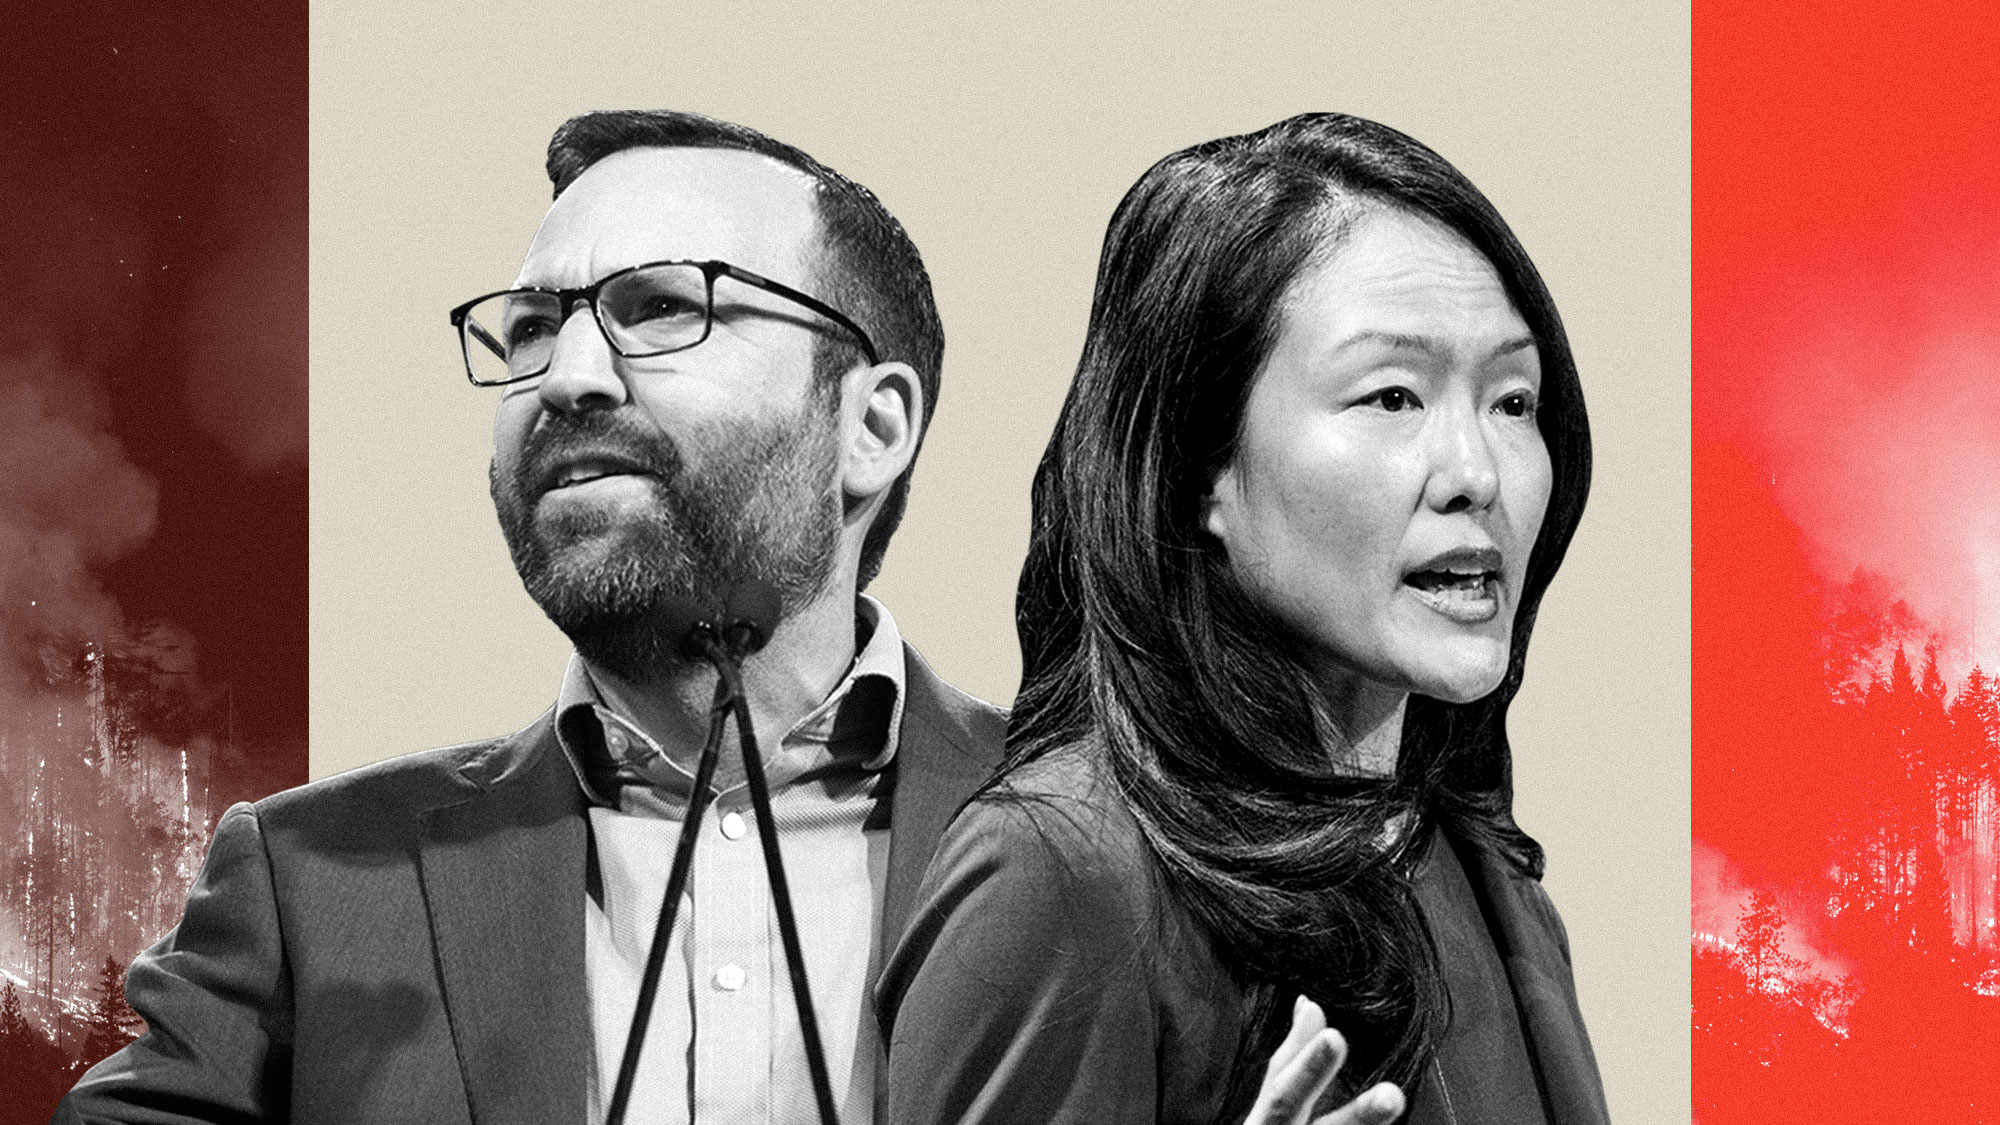
McIntyre, drawing on years of professional experience as a real estate broker, spent months locked in bureaucratic warfare with 10 different adjusters and dozens of FAIR Plan representatives. Her efforts yielded nothing. Employees deflected her inquiries at every turn, hiring third-party adjusters failed to break the deadlock, and her attorney expressed profound confusion regarding the FAIR Plan’s stubborn obstruction. Even as the vast majority of her neighbors cleared away heavy debris and began constructing modern, fire-resilient homes—many scaling up significantly in size from their original structures—her damaged bungalow sat abandoned and stained by smoke.
It was not until late August, more than a year and a half after the wildfire struck, that she was finally able to commence repairs on her house. The funding did not come from insurance payouts, but rather from a nearly $200,000 federal loan that she will eventually be required to pay back. To compound her difficulties, the FAIR Plan subsequently attempted to cut off her temporary housing allowances, arguing that basic power and water services had been restored to her neighborhood and demanding that she return home—disregarding the reality that her property still featured boarded-up windows and a scorched exterior. Meanwhile, Liberty Mutual dealt another blow by notifying her that they would be canceling the remainder of her non-fire coverage.
"The next time a fire comes through, I’m just going to light it on fire, because I’m not going to go through this again," McIntyre said wryly while standing in her doorway as heavy construction machinery rattled down the street among neighboring rebuilding projects.
The High Stakes of an Overlooked Office
Ensuring that everyday Californians have access to reliable and affordable property insurance ultimately falls to an elected official that many residents have likely never encountered: the insurance commissioner. As one of only eight statewide elected executive positions in California, the commissioner holds sweeping regulatory authority over the companies that provide fire, home, and automotive coverage across the Golden State.
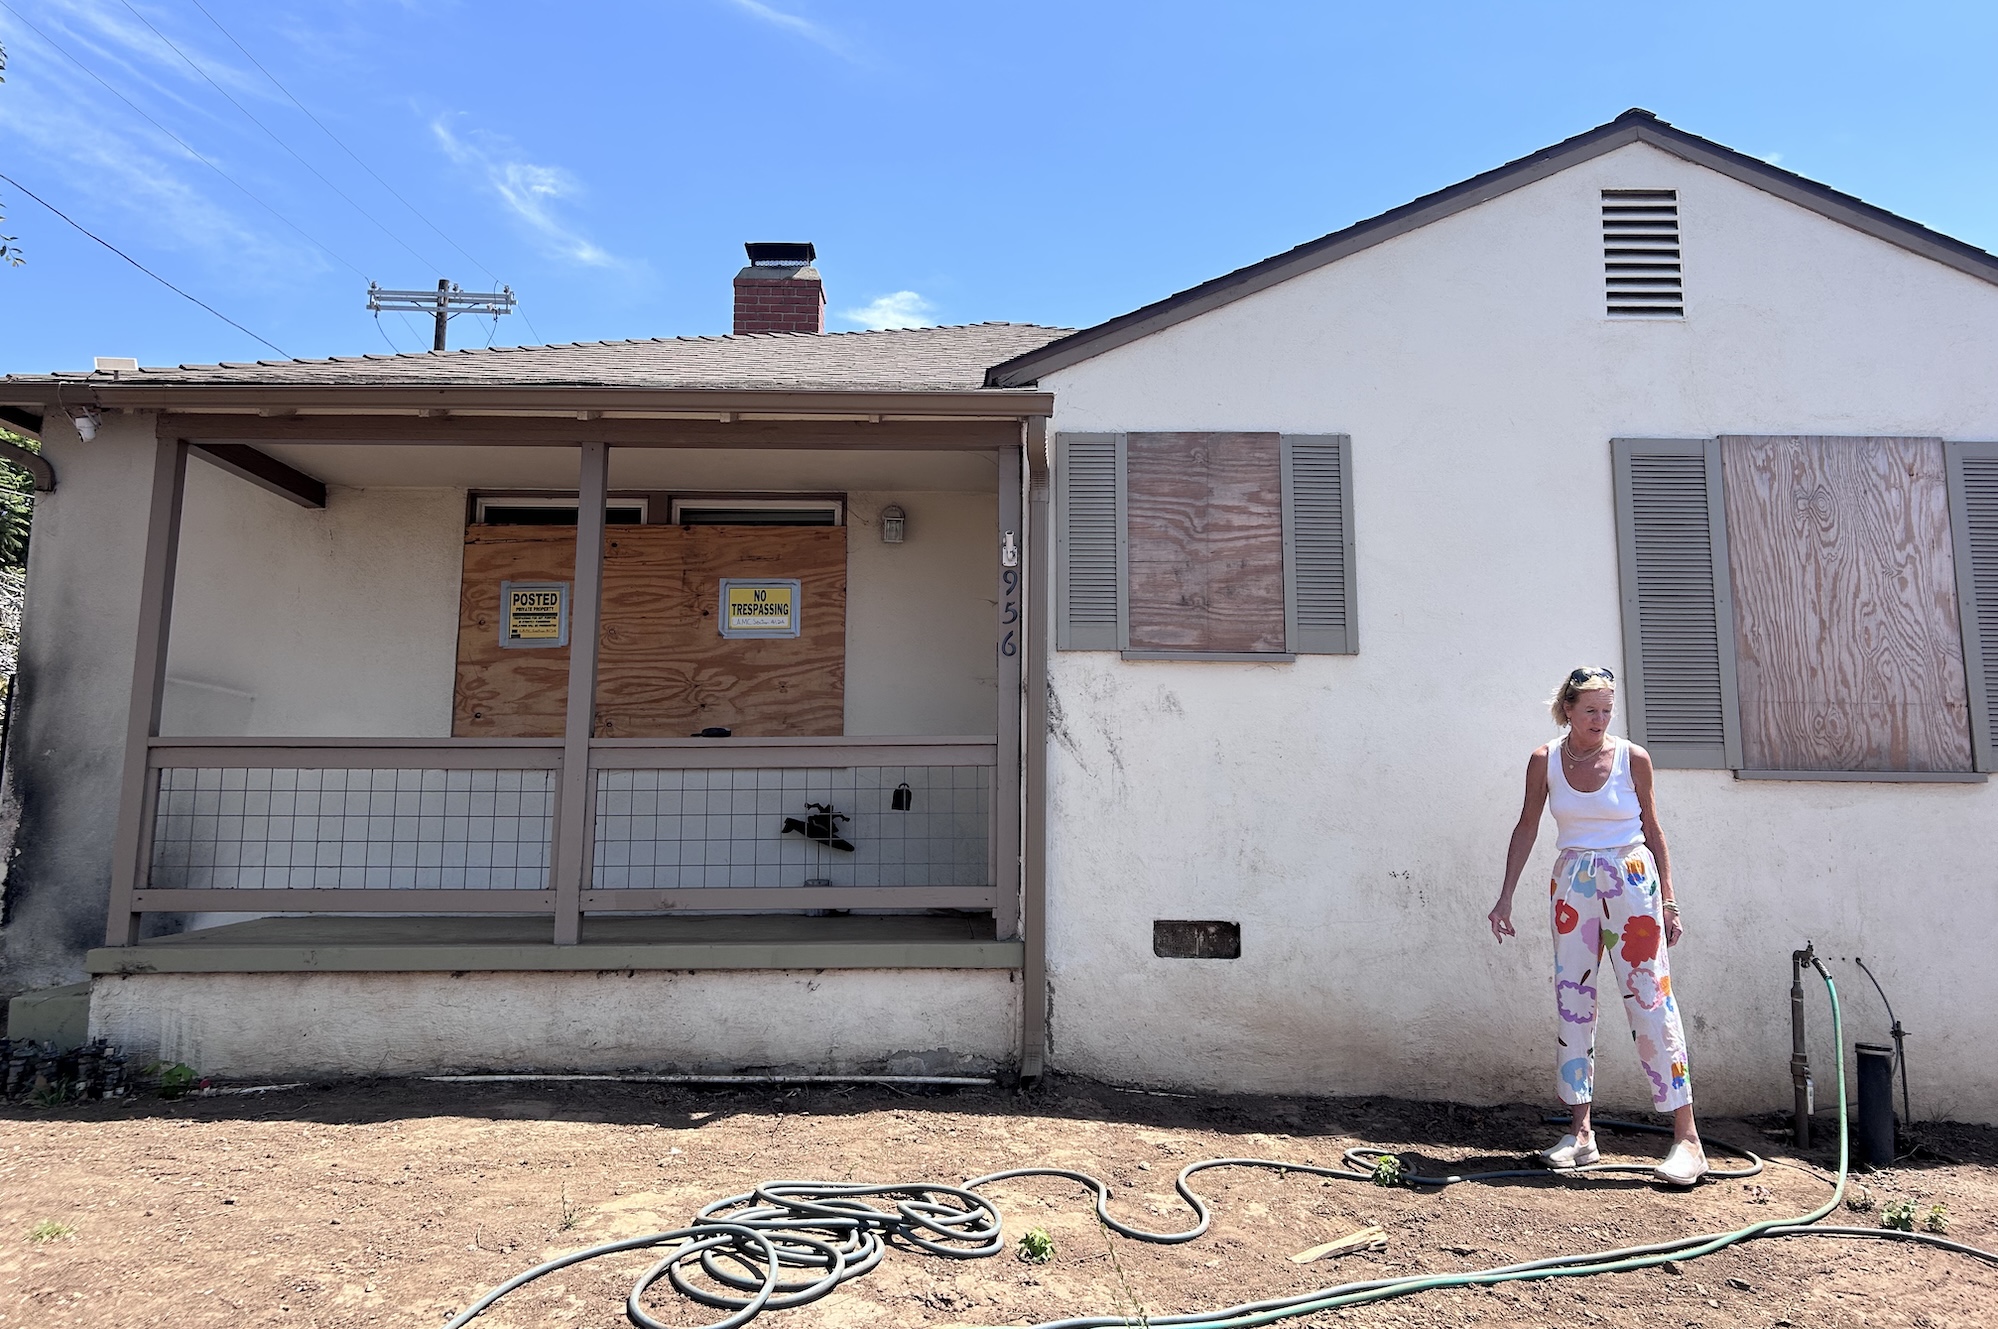
Over the past eight years, the incumbent insurance commissioner presided over a period widely characterized by industry insiders, consumer advocates, and politicians alike as a total disaster, a severe crisis, and an outright collapse of the state’s residential property insurance market. Now, as the current commissioner terms out of office, two prominent Democratic candidates—State Senator Ben Allen and former San Francisco Supervisor Jane Kim—have emerged, each arguing they possess the roadmap to fix it. Their competing campaigns embody a deeper ideological debate within the Democratic Party regarding how society should adapt to the accelerating impacts of climate change. Allen, an established legislator representing Pacific Palisades, advocates for restructuring and stabilizing the private market, while Kim, a progressive organizer from San Francisco, argues that the concept of a private insurance market is fundamentally broken and must be replaced entirely.
Whoever secures victory in November will inherit an insurance apparatus battered by a decade of catastrophic wildfires, widespread policy cancellations by fleeing insurers, and unprecedented market volatility. Decades of aggressive suppression, poor forest management, and the pressures of a warming planet have transformed California’s sprawling woodlands into dangerous tinderboxes, a threat projected to escalate as global temperatures rise. The modern crisis began in earnest with a string of unprecedented wildfires between 2015 and 2020. Those historic blazes scorched approximately 4 million acres and obliterated 35,000 structures, many located in regions with no prior history of catastrophic fire activity. Major carriers like State Farm and Farmers were forced to disburse billions of dollars in claims—wiping out the cumulative profits they had generated from writing fire insurance policies across the state over the preceding two decades.
Insurance executives maintained they had been charging Californians rates that were far too low to match the real risk, but property insurance pricing lacks the elasticity of commodities like gasoline or paper towels. Carriers are legally required to petition the state insurance commissioner for approval before implementing any rate hikes. California historically maintained a rigid stance against steep price increases, blocking attempts by insurers to pass the immense post-fire financial burden directly onto state homeowners. The industry’s retaliatory response was swift: companies dropped tens of thousands of policyholders across the state, while major players like State Farm announced they would withdraw entirely from writing new policies in California.
"There’s something broken that so many of us are facing the same issues," McIntyre noted, "and they just think they can just roughshod right on over all of us."
The shrinking availability of coverage is rippling outward, damaging the broader state economy. Approximately one in seven California realtors reported having a residential home sale fall through in 2024 due to insurance complications, the state-backed FAIR Plan exhausted its available claims capital, and average insurance premiums have continued their steep climb. This squeeze is no longer confined to traditionally high-risk wilderness areas; homeowners in historically low-risk zones are increasingly finding it difficult to secure policies.
The outcome of the November election will directly dictate the trajectory of insurance bills for millions of residents and determine the long-term viability of fire-prone communities throughout the state. Furthermore, the contest serves as a broader bellwether for how American voters wish to navigate the expensive and complex realities of climate adaptation.
Roots in the Wildland-Urban Interface
While the insurance crunch is a contemporary crisis, its structural roots span a century of development. Over the last hundred years, California permitted the construction of millions of homes within the "wildland-urban interface"—the highly flammable transition zones wrapping around major urban centers. Developers pushed outward into the mountainous terrain surrounding Lake Tahoe and the arid desert hills east of San Diego, frequently building without comprehensive fire-mitigation standards, utilizing wooden sidings and combustible fences on tightly packed lots. These are the exact communities that have borne the brunt of recent wildfire disasters, and they are the areas where private insurers are now refusing to renew policies en masse.
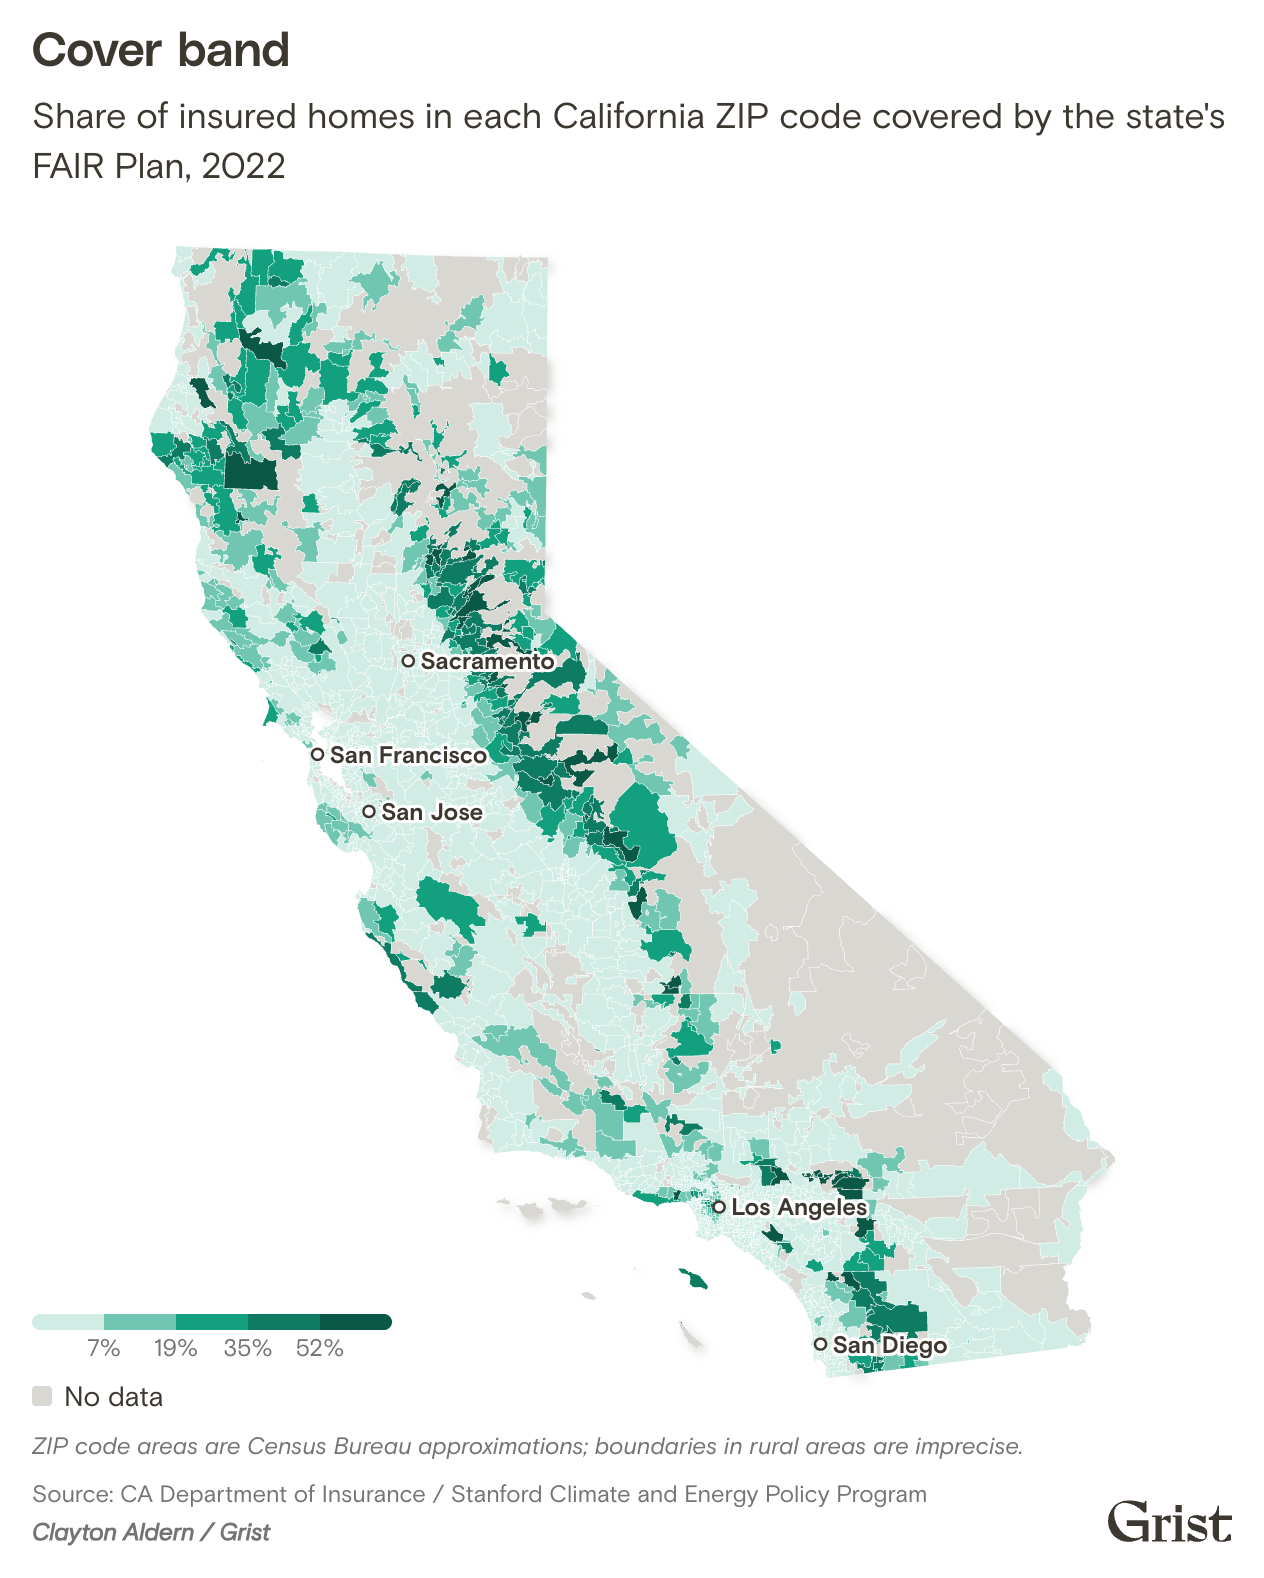
This history of high-risk real estate expansion has generated what insurance scholar Carolyn Kousky describes as "a tale of two markets." While rates experienced modest, predictable ticks upward in sheltered urban environments like San Francisco or low-lying Fresno, the market effectively broke down in high-hazard locations such as Malibu and the High Sierra. Nearly half of all households located in high-fire-risk regions lost their private insurance coverage between 2018 and 2024. Consequently, the California FAIR Plan—originally envisioned as a minor safety net for a tiny fraction of properties—exploded in size, growing from insuring less than 1 percent of the market to roughly 5 percent today, with concentrations reaching as high as 80 percent in specific vulnerable zip codes.
California voters theoretically hold significant influence over this volatile system. While every U.S. state features an insurance commissioner, California remains one of roughly a dozen where the position is directly elected by the public. This electoral accountability was established in 1988 when voters, furious over skyrocketing car insurance rates, passed a ballot initiative transforming the role from an appointed office to an elected one.
In practice, however, it is an exceptionally difficult job. The commissioner wields the authority to approve or reject proposed rate increases and police industry compliance with state statutes, alongside overseeing the FAIR Plan. Yet, the commissioner holds limited direct leverage to force private companies to write new policies or mandate regional wildfire risk reduction.
"The insurance commissioner has a lot of power and authority himself or herself that they should use, but the insurance commissioner alone cannot address these challenges," explained Dave Jones, who served as commissioner from 2011 to 2019.
The outgoing commissioner, Ricardo Lara, spent nearly his entire tenure navigating the fire-induced market collapse. Lara’s approach vacillated between cooperating closely with insurance executives and attempting to crack down on them, risking further industry flight. After initially pledging to reject insurance industry campaign contributions, he later accepted donations, a move that drew scrutiny when rate increases were delayed, prompting carriers like State Farm to shed additional policies.
Lara ultimately attempted to broker a grand bargain with the industry. He authorized carriers to pass the cost of reinsurance—insurance purchased by insurance companies to cover catastrophic losses—directly onto consumers, while also permitting the adoption of forward-looking catastrophe models to predict future risk, a practice already standard in most other states. In exchange, insurers committed to writing new policies within hazardous fire zones. However, the agreement contained substantial loopholes that allowed companies to meet their quotas without servicing the highest-risk regions, leaving the FAIR Plan to absorb even more market share following the Los Angeles fires of 2025. Lara later remarked in an interview that the insurance industry had "bullied" him.
Two Visions for the Future of California Insurance
Despite the formidable challenges inherent to the office, a dozen candidates entered the primary race to succeed Lara. The crowded field featured four Democrats, five Republicans, and two independents, most operating without the funding required for comprehensive statewide campaigns. The primary results surprised political observers: the top two vote-getters to advance to the November runoff were both Democrats.
Jane Kim, a former San Francisco supervisor and ally of Bernie Sanders who campaigned on a platform of establishing a government-run single-payer program for disaster insurance, finished in first place with roughly 27 percent of the vote. State Senator Ben Allen, who represents Pacific Palisades and stands as one of the legislature’s foremost policy experts on insurance, secured the second-place spot.
Allen and Kim share several policy goals. Both support streamlining standard insurance policies, compelling companies to disclose their spending and fossil fuel investments, and expanding the FAIR Plan’s coverage mandate to include smoke and ancillary damage—a reform that would have spared McIntyre months of bureaucratic delays. Both have pledged to crack down on carriers that intentionally stall or nickel-and-dime policyholders following disasters, and both have rejected campaign contributions from the insurance industry.
Their fundamental divergence lies in how to transition policyholders off the FAIR Plan and stabilize the broader market. Allen contends that if the state permits appropriate rate adjustments for risky properties, invests heavily in hardening vulnerable homes, and implements data-driven risk measurement, private insurers can be enticed back to rebuild a healthy market ecosystem. Kim, conversely, advocates for discarding the private market for disaster coverage entirely. She proposes establishing a universal, state-run public insurance program for all homes and natural disasters, effectively replacing private property insurers and the FAIR Plan. Rather than generating profits for corporate investors, excess revenues would be funneled back into hardening older homes against wildfires. Private carriers would still be permitted to offer coverage for non-catastrophic perils like burglary, but the state government would assume total responsibility for fire insurance and claims administration, drawing inspiration from public models in places like France and New Zealand.
This philosophical clash exposes a deeper debate over whether private markets can successfully adapt to the reality of climate change.
Allen decided to run for the commissioner post after witnessing the Palisades Fire devastate a substantial portion of his legislative district, uprooting the lives of friends and acquaintances. Having spent years leading legislative committees focused on insurance, energy, and wildfire mitigation, he frames his candidacy around deep institutional knowledge.
"I think we need someone in this office who really understands climate science, who understands the markets, who understands the legislature," Allen said.
Rather than pursuing a massive statutory overhaul like Kim’s public fund proposal, Allen emphasizes the concept of poder de convocatoria, or convening power. He aims to bring together state agencies, local governments, and the insurance industry to collaborate on reducing wildfire risk while cajoling private carriers back into the market. He recently secured passage of a bill providing low-interest loans to homeowners seeking to fire-harden their properties, favoring a compromise that pairs expedited rate decisions with strict penalties for claims delays.
Kim’s alternative proposal has generated significant momentum. She outperformed Allen across numerous counties in the primary—including Allen’s home county of Los Angeles—while performing respectably in rural and conservative regions. She attributes her strong showing to widespread voter frustration with the insurance sector.
"There’s this sense of immense unfairness, and once we articulate the problem, and then on top of that, actually propose big policy ideas, I think that that resonates," Kim noted.
Critics, however, remain skeptical of a government takeover. Former commissioner Dave Jones argued that Kim’s model suffers from critical flaws, warning that keeping prices artificially low for sprawling estates in high-hazard zones would fail to account for true underlying risk. Furthermore, California insurance regulations require carriers to hold tens of billions of dollars in liquid reserves to cover major loss events, capital that a state-run program would struggle to secure amid ongoing budget constraints.
"Not only does she not come clean as to where the money’s going to come from, if her thought is that it’s going to come from the general fund of the state of California, good luck," Jones said.
Recognizing potential legislative hurdles for a single-payer insurance system, Kim has floated a fallback strategy: transforming the existing FAIR Plan into a public resilience vehicle. By levying an additional fee on the major insurers that fund the FAIR Plan, she argues the state could generate capital specifically dedicated to home hardening.
For all their shared ground, the core disagreement remains: Allen believes private insurers can be reformed and compelled to manage climate risk, while Kim argues the industry is structurally incapable of prioritizing public safety over profit.
The Daunting Reality of Risk Reduction
Regardless of which candidate wins in November, the physical task of reducing wildfire risk remains exceptionally difficult.
Consider the experience of Tony Byers, a retired electric utility worker and longtime resident of Placerville, an old mining town nestled in the forested foothills east of Sacramento. After years with AAA, Byers was dropped following a 2022 fire that swept through a nearby section of the Sierra Nevada. State Farm subsequently quoted him a policy before rejecting him over a disputed proximity to a fire hydrant. He eventually secured coverage with an online insurer, Lemonade, even paying out of pocket to remove flammable trees at the company’s behest, only to be notified last year that the firm was withdrawing from California entirely. Today, he relies on the FAIR Plan, paying $3,400 annually for fire coverage alone—triple his previous rate. Living at the end of a narrow mountain road, retrofitting his property to meet private market standards would require tens of thousands of dollars, an expense far beyond his retirement budget.
Conversely, homeowners with substantial financial resources can bypass the standard market entirely. Kevin Roberts, a retired golf course owner living in the affluent Huntington Palisades neighborhood near the Palisades Fire burn scar, was unable to secure standard fire coverage from major carriers like State Farm. Instead, he turned to Chubb, a boutique insurer operating within California’s "surplus lines" market, which is largely exempt from state rate regulations. Chubb charges Roberts more than $30,000 a year in premiums, but ultimately delivered a $2.65 million payout for smoke damage following the fire. The state’s surplus lines market has doubled over the past four years, growing to approximately 1.3 million policies as wealthy residents seek unregulated coverage.
"You’ll pay more, but if you need them, they’ll deliver," Roberts said.
Scaling risk reduction across California’s legacy housing stock stands as one of the most complex climate adaptation challenges in the United States. Finding capital to assist vulnerable homeowners is only part of the equation; executing effective retrofitting across millions of older properties presents logistical hurdles of historic proportions.
In Lake County, north of San Francisco, a poverty-fighting nonprofit called North Coast Opportunities became the first recipient of a $117 million state grant program designed to harden entire communities against wildfire. The organization targeted Kelseyville, a densely packed neighborhood clinging to a windy mountain ridge where roughly 85 percent of the land area has burned since the turn of the century.
Through the program, participating homeowners receive roughly $70,000 to fund structural and landscaping modifications designed to prevent fire ignition, such as clearing surrounding vegetation, replacing vinyl siding with fiber cement, and removing combustible wooden decks. Yet, even with state funding, achieving community-wide participation has proved painstaking, requiring coordination with local contractors and hardware stores while overcoming initial resistance from residents attached to traditional building styles.
"What creates an insurable community is for the whole community to have buy-in," said Deanna Fernweh, the program manager. "It’s changing the mentality, because they’re like, ‘Well, we’ve always done it this way.’"
The initiative highlights the sheer scale of the deficit facing the next commissioner. The grant project services only about 300 out of 1,200 eligible homes in the neighborhood, leaving the vast majority of at-risk properties across the county without access to mitigation funding. Retrofitting existing homes for fire resilience often costs significantly more than constructing new fire-resistant structures, meaning statewide hardening efforts would ultimately require tens of billions of dollars.
As Steve Hawks, director of wildfire at the Insurance Institute for Business & Home Safety, noted, "A home is only as strong as the weakest link. If you leave a weak link on the table, a fire of [significant] magnitude can exploit any vulnerability."
Ultimately, both candidates acknowledge that addressing the crisis requires substantial financial investment, much of which will inevitably flow from California residents. As Allen observed, risk does not simply disappear; it gets reallocated. The affordability challenge is not merely a matter of keeping pace with inflation, but of paying down decades of accumulated high-risk development.
The scale of the undertaking is immense, but the societal stakes are higher still. When individuals purchase insurance, they are securing more than the legal right to own a home or a vehicle; they are buying into a shared social contract in which the community absorbs collective risk. As a cornerstone of economic participation, a stable insurance market reflects a society’s capacity to pull together, ensuring that no home is left so vulnerable to a warming world that its preservation becomes unaffordable to the rest of society.