
The modern economic landscape is increasingly populated by an eclectic collection of cleverly named consumer segments. One household features two incomes, no children, and a dog. Another earns a substantial salary yet has managed to accumulate very little long-term wealth. A third demographic is old enough to vividly remember the screech of dial-up internet access, yet young enough—and financially flexible enough—to spend heavily on craft supplies and creative pastimes.
Meet the DINKWADs, the HENRYs, and the elder millennials. While these catchy and slightly humorous labels often invite a smile in marketing circles, their purchasing behaviors offer a vital and practical reminder for businesses, banks, and retailers. People belonging to similar age groups or broad demographic bands can have wildly different claims on their money, entirely distinct financial priorities, and fundamentally unique lifestyle motivations. Understanding these nuances has become essential for institutions looking to capture the attention and loyalty of today’s diverse consumer base.
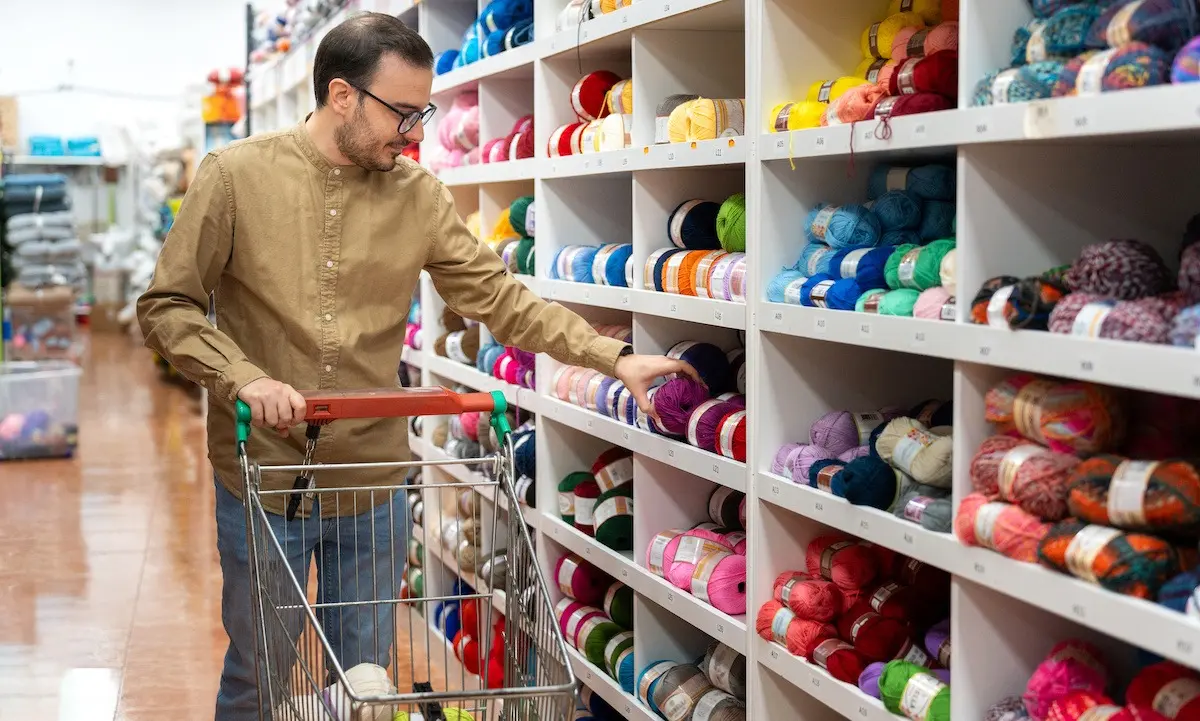
To understand the complexity of modern consumer behavior, one can start with the demographic known as elder millennials. According to a study published in August by the Bank of America Institute, older millennials spend more per customer on hobbies and creative pastimes than any other living generation. Yet, this same group also contends with a severe time crunch, reporting the least amount of daily leisure time among consumers—averaging just about four hours and 15 minutes a day.
The Bank of America report defined its older millennial cohort as individuals born from 1978 through 1988. However, anyone born closer to the beginning of that range might reasonably object to the millennial designation, feeling they share more cultural and financial traits with Generation X. This little border dispute highlights a broader truth about modern consumer analytics: a generation’s exact edges often depend entirely on who drew the chart and what metrics they chose to emphasize.
Bank of America suggested that older millennials may be purchasing hobby supplies not just for themselves, but also for their children, blending family time with creative outlets. Across all of the bank’s credit and debit cardholders, overall hobby spending rose 7.9% in August compared to the same period a year earlier, while the total number of individual purchases increased by 3.4%. This widening gap between spending growth and transaction growth implies that even modest pastimes and everyday crafts are becoming noticeably more expensive. Consequently, a modern family might choose an afternoon of arts and crafts at the kitchen table over an expensive family vacation, only to discover that inflation has found a way to raise the prices of simple fun, too.
Beyond the generational debates, consumer researchers are tracking entirely different household structures, such as the DINKWADs—an acronym for dual-income couples with no kids, but with a dog. A recent survey conducted by OnePulse involving 250 DINKWADs in the United Kingdom explored the profound financial impact of these canine companions. The survey revealed that 44% of respondents had planned an entire holiday or vacation specifically around their dog, prioritizing pet-friendly destinations and accommodations above all else. Furthermore, nearly a third of those surveyed had chosen a new vehicle based heavily on how well their dog fit inside the cabin. While these findings originate from a U.K. survey rather than a comprehensive census of American pet owners, the underlying spending logic travels easily across borders and oceans. The four-legged passenger in the household can decisively influence major financial commitments, including vehicle purchases, travel itineraries, vacation rentals, and even household insurance policies.
The broader parentless household category remains remarkably substantial in the United States. Data from the Pew Research Center indicates that 12% of married couples in the U.S. with at least one spouse in their 30s or 40s lived with two incomes and no children in 2023, representing a significant increase from 8% a decade earlier. While the Pew Research Center did not track how many of these dual-income households owned dogs, the popular DINKWAD label neatly captures a specific, lifestyle-driven subset within that larger socioeconomic shift.
Another prominent and frequently discussed consumer label is HENRY, which stands for high earners who are "not rich yet." This group presents a fascinating paradox where their annual income and their accumulated net worth tell entirely different stories. In July, insurance provider Chubb published data from a comprehensive survey of 1,000 self-identified HENRY collectors, ranging in age from their early 20s to 45. Among these affluent yet wealth-building collectors, 64% owned luxury watches or fine jewelry, while 51% actively collected art, antiques, or other high-end collectibles. Many respondents noted that they view their collections not only as sources of personal pleasure and aesthetic enjoyment, but also as potential stores of long-term value and investment diversification. Chubb’s findings revealed that 47% of these collectors had insured their valuable items. For these consumers, a high professional salary provides the immediate liquidity to fund luxury purchases, while protecting those assets creates an entirely new set of financial planning decisions.
Perhaps the label with the least amount of comic potential, but arguably the most significant implications for financial services and wealth management, is the solo ager. Solo agers are older adults who live independently without a spouse or a partner at home. Research published last year by AARP found that many solo agers deeply value the personal freedom, autonomy, and household control that this living arrangement provides. At the same time, their unique domestic circumstances can fundamentally alter how they choose professional financial advice, plan for long-term health and elder care, guard against increasingly sophisticated digital scams, and decide who holds legal power to act on their behalf if the need arises.
A closer look reveals that these consumer groups often overlap in complex ways. An elder millennial could easily be part of a DINKWAD household or fit squarely into the HENRY wealth category. Ultimately, these descriptive names are most useful when they point toward a real, measurable financial decision or behavioral trend, rather than when they simply serve as catchy costumes for a temporary corporate advertising campaign. For merchants, traditional banks, and modern payment providers, the most reliable clue to consumer behavior is often found by examining what a customer is trying to support—whether that is a child’s hobby, a beloved family dog, a valuable collection of art, or a fiercely independent life. Birth years and demographic acronyms tell only a portion of that evolving story.